
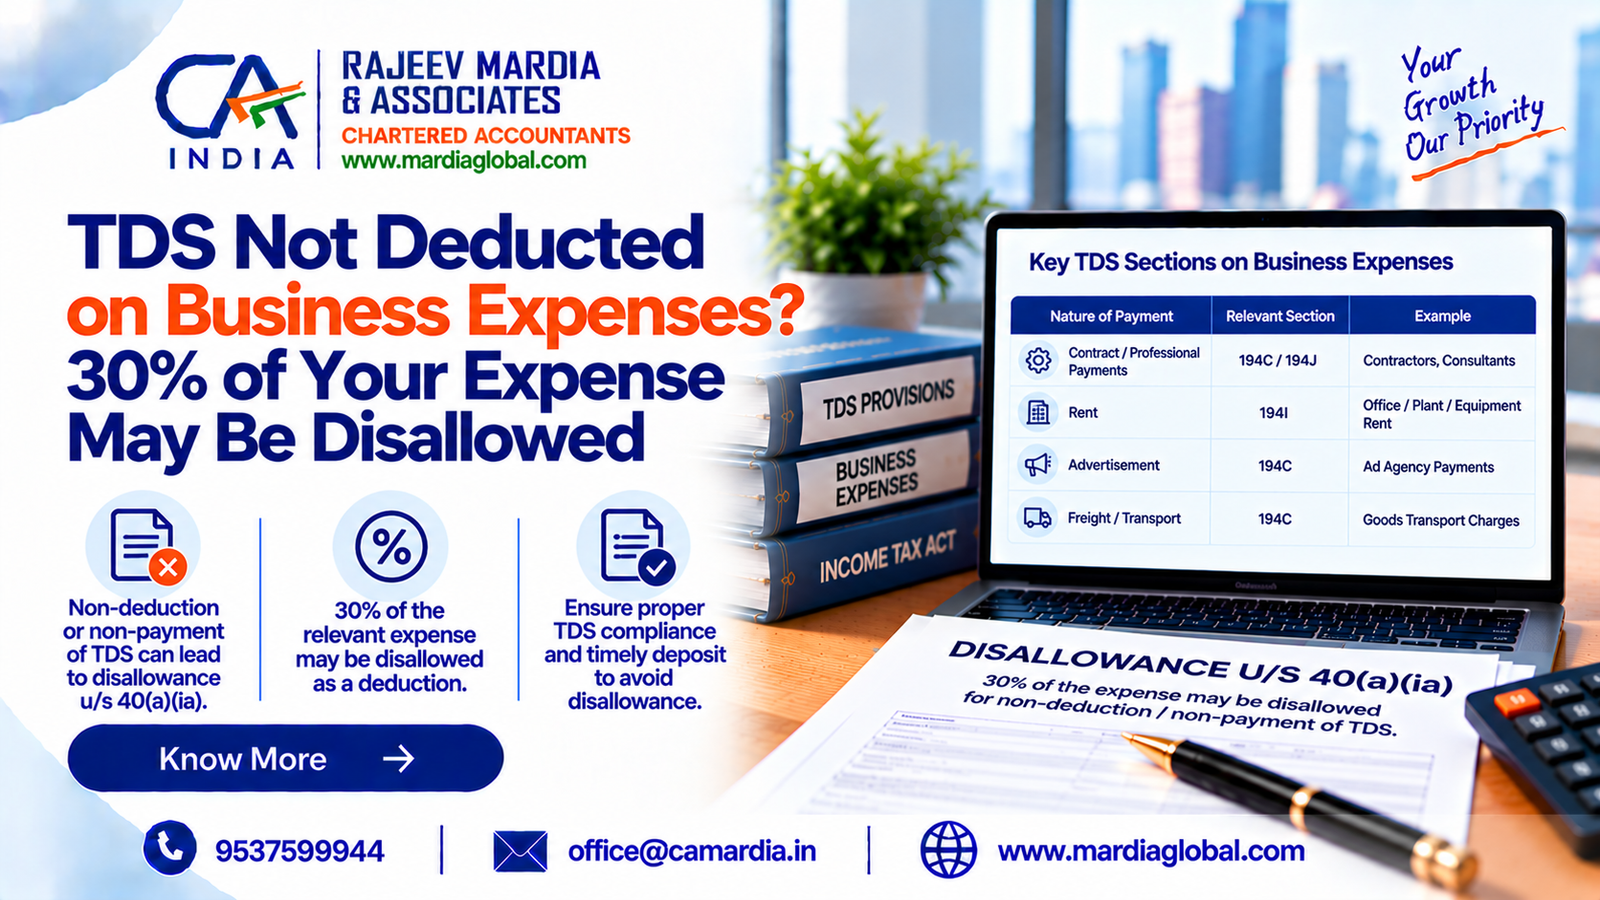
TDS Not Deducted on Business Expenses? 30% of Your Expense May Be Disallowed
And Associates
Businesses finalising their Income Tax Returns for FY 2025-26 should carefully review expenses on which Tax Deducted at Source (TDS) was applicable. Under Section 40(a)(ia) of the Income Tax Act, 1961, failure to deduct TDS on specified payments to residents, or failure to deposit the deducted tax within the prescribed time, can result in 30% of the relevant expenditure being disallowed while computing taxable business income.
What Happens if TDS Was Deducted but Deposited Late?
A delayed TDS deposit does not necessarily mean that the expense will be disallowed. Where TDS was deducted during FY 2025-26 and deposited on or before the applicable due date for filing the Income Tax Return under Section 139(1), the expenditure can generally remain deductible, although interest may still apply for the delayed deposit.
However, where TDS is deducted or deposited after the relevant deadline, the corresponding disallowed expenditure may become deductible in the year in which the tax is subsequently paid, subject to the statutory conditions.
Why Does This Matter to Businesses?
Companies, LLPs and other businesses should reconcile their professional fees, contractor payments, commission, rent, interest and other TDS-applicable expenses before finalising their Income Tax Returns.
Special attention should be given to expenses recorded through year-end journal entries, outstanding TDS liabilities and payments made after the financial year.
Businesses should also examine whether any available statutory relief applies where the recipient has already disclosed the income and paid the applicable tax.
A proper expense-wise TDS reconciliation can help businesses avoid incorrect deductions, additional tax liabilities and unnecessary disputes during assessments.
Mardia Global | Tax & Accounting Insights for Businesses in India