
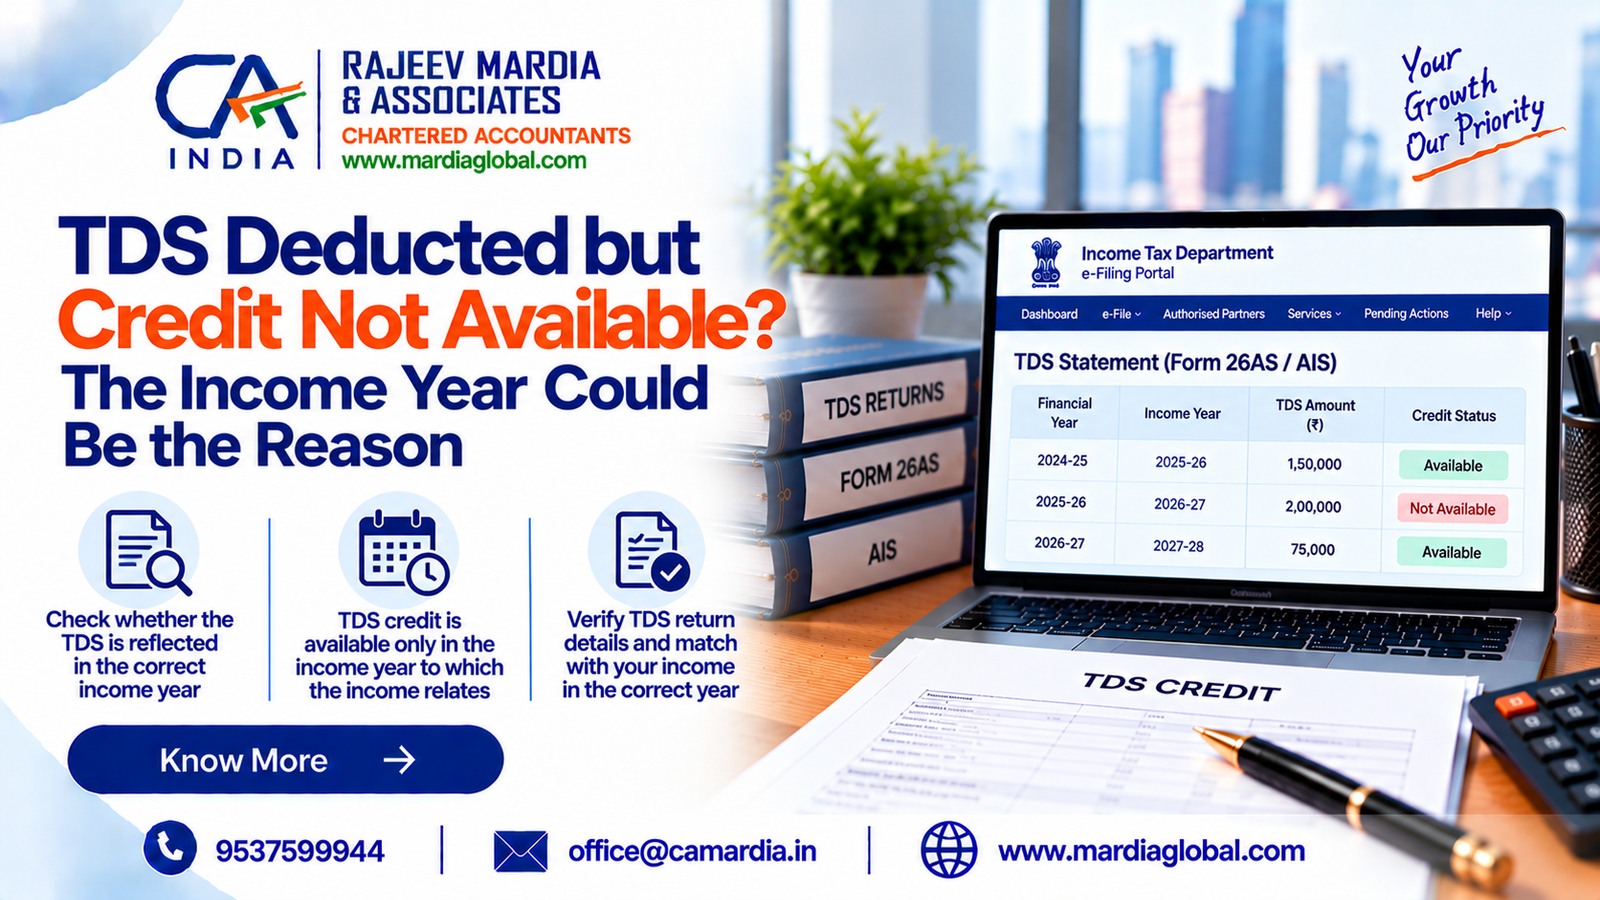
TDS Deducted but Credit Not Available? The Income Year Could Be the Reason
And Associates
A business may find that TDS deducted by its customer is visible in Form 26AS or AIS, but the corresponding credit cannot be fully claimed in its Income Tax Return. One important reason is a mismatch between the year in which TDS was deducted and the year in which the related income is taxable.
Under Rule 37BA of the Income-tax Rules, 1962, TDS credit is generally allowable in the assessment year in which the corresponding income is assessable. Where income is taxable over multiple years, the related TDS credit is ordinarily allocated proportionately across those years.
What Should Businesses Check?
For AY 2026-27, businesses should reconcile TDS appearing in Form 26AS and AIS with the income reported in their financial statements and Income Tax Return.
Where TDS relates to income taxable in a subsequent year, the appropriate credit may need to be carried forward rather than claimed entirely in the current year.
The Income Tax Department has also clarified that TDS deducted in March 2026 but deposited after 1 April 2026 continues to relate to AY 2026-27, provided the deductor reports it correctly.
Why Does This Matter to Businesses?
Incorrect allocation of TDS credit can result in return-processing mismatches, reduced refunds or additional tax demands.
Finance teams should therefore reconcile customer-wise TDS deductions, income recognition, Form 26AS/AIS and unclaimed TDS carried forward before finalising their returns.
A proper year-wise TDS reconciliation helps ensure that tax credits are claimed in the correct period and reduces avoidable disputes during return processing.
Mardia Global | Tax & Accounting Insights for Businesses in India